
Here’s something that surprised me when I dug into commercial space stations: NASA’s plan for life after the ISS isn’t to build a new government space station. It’s to become a tenant.
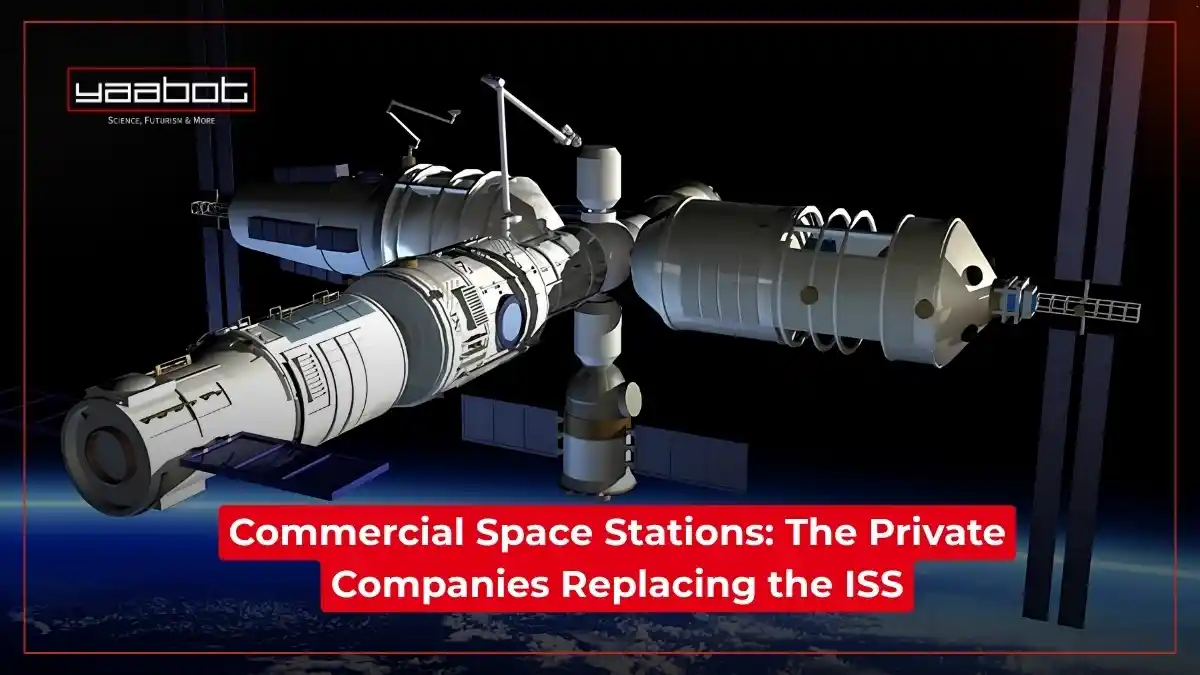
When the International Space Station retires in 2030, it won’t be replaced by another government-owned station. Instead, NASA plans to assign private companies to operate the new space stations.
I think that’s a bigger deal than most coverage gives it credit for. The future of human presence in low Earth orbit sits in the hands of private space station companies, some of which are building actual hardware right now, while others are still working out whether the business model holds. The answers aren’t all flattering.
Here’s what I think you need to understand about where this is going, who’s building it, and what it actually means.
Key Takeaways
- The International Space Station is scheduled to retire in 2030, and NASA is funding private companies to build its replacement in LEO.
- At least five commercial space stations projects are in active development, including Axiom Station, Orbital Reef, and Starlab.
- The commercial space station market is valued at $4.5 billion in 2025 and projected to reach $16.4 billion by 2033 at a 35% CAGR.
- Revenue streams include microgravity research, in-space manufacturing, government contracts, and space tourism.
- NASA expects to save $1.5 billion per year after the ISS retires, freeing up budget for deep space programs.
What Are Commercial Space Stations?
Commercial space stations are an orbital facility owned and operated by a private company rather than a government. The company designed it to generate revenue by selling access to space, whether through lab time or luxury stays for paying tourists.
The keyword is access. Unlike research vessels or defense satellites, a commercial space station is infrastructure. Multiple customers use it at the same time for different purposes.
Differences from government space stations
The International Space Station is a government program. Taxpayers funded it, intergovernmental agreements enabled its construction, and NASA, Roscosmos, ESA, JAXA, and CSA operate it.
Private space stations work differently:
- Private investors, NASA contracts, and pre-sold research agreements finance them.
- They must generate their own revenue to cover operating costs.
- They can move faster on design decisions because they don’t require the same layers of political approval.
- They carry more financial risk, especially in the early years when the customer base is still developing.
The shift from government-run to commercially-run orbital infrastructure isn’t just about who cuts the checks. It changes the incentive structure for everything from module design to pricing.
The Legacy of the International Space Station

How the ISS enabled the commercialization of space
The ISS has been continuously inhabited since November 2000. Over 25 years, it has hosted more than 270 people from 21 countries, conducted tens of thousands of experiments, and served as the proving ground for almost everything we know about long-duration human spaceflight.
It also served as an early market-maker for the commercial space industry. SpaceX’s Crew Dragon and Cargo Dragon were both funded through ISS resupply contracts. Without that guaranteed government revenue, it’s unlikely SpaceX would have developed reusable rockets on the same timeline. The same logic applies to Northrop Grumman’s Cygnus cargo vehicle.
The ISS didn’t just do science. It built the supply chain for the commercial space industry that now wants to replace it.
Why the ISS is being phased out
Age is the simple answer. The ISS was never designed to last this long. Hardware that’s been in orbit for over two decades requires constant maintenance, and some of the structural limits are getting harder to work around. NASA has documented that the Russian segment in particular is showing signs of wear, including persistent air leaks.
But cost is the real driver. The ISS costs NASA roughly $3 billion per year to operate. The agency has decided that money is better spent on the Artemis lunar program and deep space exploration. By retiring the ISS and paying commercial operators for station access instead, NASA expects to save $1.5 billion annually, a figure projected to rise to $1.8 billion after 2030.
ISS Replacement: What Comes After 2030?
There is no single ISS replacement. That’s the point.
NASA’s Commercial LEO Destinations (CLD) program is designed to fund multiple private space stations competing for government contracts, research tenants, and eventually tourists. Rather than building and owning the next station itself, NASA becomes a customer, the same way a company might rent office space rather than own a building.
As of 2026, three projects have received NASA CLD funding and are building hardware:
- Axiom Station (Axiom Space + Thales Alenia Space)
- Orbital Reef (Blue Origin + Sierra Space)
- Starlab (Voyager Space + Airbus)
There are also newer entrants. Vast Space’s Haven-1 is scheduled to launch in 2027 atop a SpaceX Falcon 9, and the Gateway Foundation’s VERA Station is a longer-term concept for a rotating gravity station.
The future of space stations in LEO isn’t one facility. It’s a market.
Timeline of Commercial Space Stations (2025–2030)
| Year | Expected Development |
| 2025 | Commercial LEO programs accelerate as private space companies finalize station designs and partnerships. |
| 2026 | Hardware development and testing continue for Axiom Station, Orbital Reef, and Starlab. |
| 2027 | Planned launch window for Axiom’s first module and Orbital Reef’s early deployment phases. |
| 2028 | Expansion of modular station infrastructure and increased private astronaut missions. |
| 2029 | Commercial operators prepare for larger-scale research, manufacturing, and tourism operations in LEO. |
| 2030 | International Space Station retirement expected, with private stations positioned as ISS replacement infrastructure. |
Why the World Is Moving Toward Private Space Stations
Growth of the commercial space economy
The numbers here are not speculative. The global space economy was valued at $418 billion in 2024 and is projected to reach approximately $640 billion by 2030. PwC’s projections put the long-term ceiling at $2 trillion by 2040.
The commercial space industry has grown because the cost of reaching orbit has collapsed. SpaceX’s reusable rockets brought launch costs down to around $2,000 per kg, compared to tens of thousands just a decade ago. And when it becomes cheaper to get to space, every boardroom pitch gets easier to justify.
Demand for orbital research and manufacturing
Microgravity produces things you can’t make on Earth. High-purity fiber optic cables, certain protein crystals used in drug development, and semiconductor structures that would be deformed by gravity all require the conditions that only orbital platforms can provide.
The in-space manufacturing market is projected at $21.3 billion by 2030, growing to $135.3 billion by 2040 at a 20.3% CAGR. Pharmaceutical companies, materials scientists, and tech manufacturers are all looking at commercial space stations as serious production facilities.
Private Investment in Commercial Space Stations
The ISS era was funded by governments. The next era is being funded by a mix of NASA contracts, venture capital, and strategic corporate partnerships.
Orbital Reef, for example, has secured backing from Amazon, Boeing, Mitsubishi Heavy Industries, Redwire Space, and Arizona State University. Starlab brought Airbus and Northrop Grumman into its consortium. They’re infrastructure investments made by companies that expect recurring revenue from orbit.
Key Space Station Companies Leading the Transition

Axiom Station
Axiom Space is probably the furthest along in terms of operational experience. The company was founded by former ISS program manager Michael Suffredini, which means the core team has actually run a space station before.
The plan is a five-module station built in phases. The first module, the Payload Power Thermal Module (PPTM), will attach to the ISS before the station retires, then detach to form the nucleus of a free-flying Axiom Station. Thales Alenia Space has already begun work on the PPTM’s primary structures.
The full station includes:
- PPTM: Power and thermal management. The first module is scheduled to launch by 2027.
- HAB-1: Crew quarters for four, propulsion, and station control (2028).
- Airlock: EVA capability and external payload hosting.
- HAB-2: Four more crew, full ECLSS support, doubles crew capacity.
- RAM Module: Research, manufacturing, and Earth observation
Later additions include SEE-1, a spherical inflatable entertainment studio, which is where the Tom Cruise space film project comes in. Yes, that’s actually planned.
Orbital Reef
Blue Origin and Sierra Space’s Orbital Reef is designed as a “mixed-use business park” in LEO. It’s probably the most technically ambitious of the three major commercial space stations projects, partly because of the Sierra Space LIFE module.
The LIFE module is an inflatable habitat, roughly 10 meters long and 8.5 meters in diameter. Sierra Space completed burst tests successfully. Inflatable modules are important because they’re small during launch but expand to much larger habitable volumes in orbit.
The station’s four core modules offer 830 m³ of total volume, enough to support 10 people simultaneously. Orbital Reef is also designed to dock with nearly every spacecraft currently in operation, including Crew Dragon, Soyuz, Dream Chaser, and Starliner.
Target launch date for first modules: 2027.
Starlab
Starlab is a joint venture between Voyager Space and Airbus, with Northrop Grumman developing its autonomous docking systems. It’s positioned as a single large station rather than a modular architecture, which is a different design philosophy from Axiom and Orbital Reef.
The involvement of Airbus is notable. They’re providing their expertise in aerospace engineering, and not just capital. Northrop Grumman’s role in autonomous docking is also strategic. If Starlab can receive cargo and crew vehicles without manual docking operations, it will significantly reduce operational complexity.
Starlab is targeting full operations by the end of the decade to coincide with ISS retirement.
Comparison of Major Commercial Space Stations
| Space Station | Company/Partners | Expected Launch Timeline | Crew Capacity | Core Focus | Key Differentiator |
| Axiom Station | Axiom Space + Thales Alenia Space | First module planned for 2027 | Up to 8 crew | Research, tourism, media | A modular station that initially connects to the ISS before becoming independent. |
| Orbital Reef | Blue Origin + Sierra Space | Initial deployment targeted for 2027 | Around 10 crew | Mixed-use orbital business park | Inflatable LIFE habitat modules with large internal volume |
| Starlab | Voyager Space + Airbus + Northrop Grumman | End of the decade | Not publicly finalized | Research and long-duration operations | Single large-station design with autonomous docking systems |
Business Models Behind Commercial Space Stations
Research and microgravity manufacturing
This is the foundation revenue stream. Universities, pharmaceutical companies, and materials researchers all need access to microgravity for experiments that can’t be replicated on Earth. Every commercial space stations will sell blocks of research time, payload hosting, and crew time for experiments.
The ISS hosted thousands of experiments over its lifetime. But the difference between private space stations is pricing flexibility and capacity scale.
Government and institutional partnerships
NASA will remain a major customer, just not the owner. Through the CLD program, the agency has already committed hundreds of millions in development contracts to Axiom, Blue Origin/Sierra Space, and Voyager/Airbus. Post-ISS, NASA will likely purchase crew time and research capacity the way it buys rides on Crew Dragon today.
Other government agencies and international space programs are also potential customers. ESA, JAXA, and others will need orbital research access after 2030. Commercial space station operators are positioning themselves as the infrastructure providers for the entire global space research community.
Long-term revenue opportunities
Beyond research, the longer-term revenue picture includes:
- In-space manufacturing: Producing products for terrestrial markets.
- Space tourism: Selling orbital stays to individuals and corporations.
- Media and entertainment: Studio time in space. Axiom’s SEE-1 module is the clearest example.
- Satellite servicing: Using the station as a base for in-orbit maintenance operations.
- Defense and intelligence contracts: Secure orbital facilities for government use.
No single revenue stream justifies the capital cost. The business case depends on stacking multiple revenue sources, which is exactly how hotels, airports, and ports work on Earth.
Space Tourism and the Rise of Orbital Experiences
Space tourism is the revenue line that gets the most press, but it’s not the only one, and right now it’s not the largest. That said, it’s not trivial either.
Axiom has already flown four private missions to the ISS. The ticket price runs somewhere north of $55 million per seat. SpaceX has run its own tourist missions. There is a real, if small, market of ultra-high-net-worth individuals willing to pay for orbital experiences.
What changes with commercial space stations are duration and repeatability. Instead of shorter ISS visits, private stations can offer much longer stays with more amenities. Axiom’s modules are designed with private crew quarters and windows. SEE-1’s spherical inflatable volume is basically a luxury cabin in orbit.
The space tourism market is still in its very early innings. But the infrastructure being built for research and government contracts also lowers the marginal cost of hosting tourists. Once the station is there and staffed anyway, each additional tourist berth is mostly incremental revenue.
Technologies Powering Future Space Stations

Modular station architecture
Modular space stations are built from interchangeable sections that can be launched separately and assembled in orbit. This matters for two reasons: no single launch vehicle has to carry the whole station, and the station can grow over time as more modules are added.
Axiom’s five-module plan is the clearest example. Each module serves a specific function and can be launched on a commercial rocket. The station starts small and expands.
Life-support and habitation systems
Environmental Control and Life Support Systems (ECLSS) are what keep people alive in orbit. They handle air revitalization, water recovery, temperature management, and waste processing.
The ISS ECLSS is a proven system, and much of what’s being built for commercial space stations is derived from it. Axiom’s HAB-2 module includes full ECLSS support. Sierra Space’s LIFE module integrates life support with its inflatable structure, which is a new technical territory.
Launch vehicles and logistics
You can’t run a private space station without cargo and crew access. The commercial space industry has solved most of this already. SpaceX’s Falcon 9 and Starship, Blue Origin’s New Glenn, and eventually other providers give station operators multiple options for resupply.
The key metric is cost per kg to LEO. SpaceX has driven that number down dramatically. Competitors are following. Lower launch costs directly improve the economics of running a commercial space station.
Challenges Facing Private Space Infrastructure
Funding and economic sustainability
The capital requirements are enormous. Building, launching, and operating a space station costs billions. NASA contracts provide some anchor revenue, but they don’t cover everything. So the private space companies need to develop enough commercial demand to cover the gap.
The honest risk is that the customer base for orbital research and manufacturing doesn’t materialize fast enough. The demand projections look compelling, but they’re projections.
Safety and regulatory frameworks
Human spaceflight has a zero-tolerance relationship with safety failures. The regulatory framework for private space stations is still being developed. NASA and the FAA have overlapping jurisdiction.
Who regulates a space tourist’s stay on Axiom Station? What liability regime applies if something goes wrong? These questions don’t have clean answers yet, and private space companies are navigating largely uncharted legal territory.
Technical complexity and operational risks
Operating in space is genuinely hard. Over the years, ISS has had air leaks, cooling system failures, and propulsion problems throughout its life. Commercial stations will face the same categories of problems with less experienced operations teams and tighter budgets.
Modular space stations also introduce the risk of assembly. Docking modules in orbit, expanding inflatable habitats, and integrating systems from multiple manufacturers all require smooth execution.
Public vs. Private Space Stations: Industry Transition
Government-led space programs vs. private ventures
The division isn’t as clean as it sounds. The ISS itself depended on private contractors for almost everything. From Boeing building the U.S. lab module to Lockheed building components. The only difference now is ownership and financial accountability.
When NASA owns the station, performance failures are political problems. When a private company owns it, they’re business failures. Private operators have stronger incentives to control costs and find revenue, while government programs have stronger incentives to prioritize safety and politics over efficiency.
Neither model is simply better. They optimize for different things.
Collaboration between NASA and commercial partners
NASA’s CLD program isn’t a handoff. It’s a structured partnership where the agency funds development in exchange for access rights and some operational oversight. NASA will still be one of the biggest customers of the commercial space stations it helped build.
The more interesting question is what happens five years in, when the commercial operators have enough confidence to push back on NASA’s requirements. That negotiation hasn’t happened yet.
The Future of Space Stations and the LEO Economy
Growth of the low-earth-orbit economy
The LEO economy is not just space stations. It includes satellite communications, Earth observation, in-space manufacturing, and eventually resource extraction and transport. Space stations are the anchoring infrastructure for human activity in this broader ecosystem.
The global space economy is expected to cross $640 billion by 2030, with commercial segments growing faster than government programs. Commercial operators in LEO benefit from the entire ecosystem. More satellites mean more demand for servicing, more Earth observation means more demand for data processing, and more human activity in orbit means more demand for habitation.
Long-term vision for space commercialization
The endgame here isn’t just a few private space stations circling Earth. It’s an orbital economy where manufacturing, research, etc., all happen routinely in space. Exactly the same way shipping and aviation became routine industries over the last century.
The Gateway Foundation’s VERA Station, with its rotating torus and artificial gravity, represents what that mature future might look like. A facility designed not for occasional scientific visits but for long-term human habitation and economic activity.
We’re not there yet. But the infrastructure being built now, Axiom Station, Orbital Reef, and Starlab, is the foundation layer.
Final Thoughts
The retirement of the International Space Station is not the end of human presence in low Earth orbit. It’s the end of government monopoly over it.
What comes next is messier, more competitive, and more interesting. Multiple private space stations are targeting different customer segments with different technical approaches. Some will succeed, some will fail, and the market will sort them out. That’s how infrastructure industries work.
I think the transition matters beyond the space community. The commercial space stations are becoming a real asset class, not just an engineering project. The companies building these stations are making a bet that demand for orbital access, from researchers, manufacturers, tourists, and governments, is real and growing. Based on the market data and the engineering progress so far, that bet looks increasingly well-placed.
The first generation of truly commercial space stations will tell us whether human civilization actually has an economic foothold in space, or just a scientific one. That’s worth paying attention to.
Frequently Asked Questions (FAQ)
The main space station companies currently building hardware are Axiom Space, Blue Origin (with Sierra Space on Orbital Reef), and Voyager Space (with Airbus on Starlab). Vast Space’s Haven-1 is also scheduled for a 2027 launch.
Yes. Axiom Space has already run four private crewed missions to the ISS. Both Axiom Station and Orbital Reef include habitation modules designed for private visitors. Ticket prices currently run above $55 million per seat, though that figure is expected to decrease as the commercial space industry scales.
The biggest challenges are securing enough commercial revenue to cover enormous capital and operating costs, navigating an evolving regulatory framework for private human spaceflight, and managing the technical complexity of assembling and operating modular structures in orbit.
