

The last time algae showed up in my feed, it was the villain, toxic blooms choking a lake and green sludge closing a beach. So the idea that this same slime could be processed into Sustainable Aviation Fuel (SAF) and power the plane I fly home on felt like a bad sci-fi pitch.
Then I started reading the actual numbers, and the pitch got more interesting.
But the real question isn’t, will my flight run on algae next year? It’s whether algae fuel can grow up fast enough to matter, and whether SAF as a whole can actually move the needle on aviation sustainability. That’s what this piece is all about.
Key Takeaways
- Sustainable Aviation Fuel is a drop-in renewable fuel that works in today’s engines, but it’s still under 1% of global jet fuel supply.
- Algae fuel is the highest-yield biofuel feedstock on paper, but it’s still pre-commercial for aviation.
- SAF can cut lifecycle emissions by up to around 80%, and up to 94% with the right feedstock.
- The biggest barrier is cost: SAF runs several times pricier than fossil aviation fuel.
- Policy, not chemistry, is now the main driver of adoption.
What Is Sustainable Aviation Fuel (SAF)?
Sustainable Aviation Fuel is jet fuel made from renewable or waste feedstocks instead of crude oil, and it’s chemically close enough to ATF with no engine changes. And that’s what matters. SAF is a “drop-in” renewable fuel, so airlines can pour it into existing aircraft and existing airport pipelines today. No new planes and no new fuel trucks.
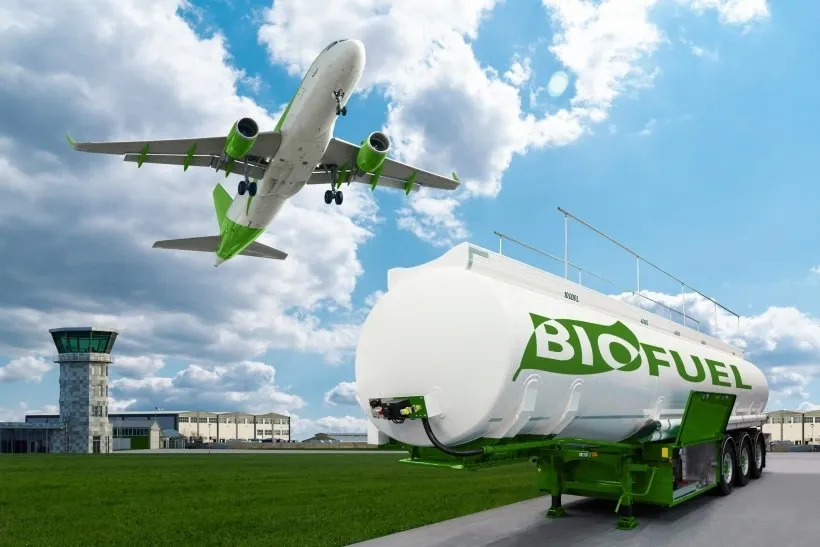
There’s no single SAF. It’s a family of production pathways, and the U.S. Department of Energy lists several approved ones. The three you will hear about most:
- HEFA (hydroprocessed esters and fatty acids): Made from used cooking oil, animal fats, and plant oils. This is the workhorse and accounts for around 80% of SAF production in the near term.
- Alcohol-to-jet: Turns ethanol or other alcohols into jet fuel.
- Power-to-liquid (e-fuels): Combines green hydrogen with captured CO2. Tiny today, but the long-game favorite because it doesn’t depend on biomass.
There are 11 certified SAF pathways in total. One interesting fact is that under the current fuel standards, SAF is capped at a 50% blend with ATF. So, most flights running on SAF are still running mostly on kerosene. Virgin Atlantic flew a transatlantic flight on 100% SAF in late 2023 as a proof of concept.
But where does algae fit into all this green technology? Right now, mostly in the lab. And that’s a gap that people need to understand.
How Algae Biofuel Could Power the Future of Aviation
Algae is the most hyped feedstock in the biofuel world for one reason: its yield. It produces far more oil per acre than any crop, and it doesn’t need farmland to do it.
The U.S. Department of Energy has estimated that algae can yield roughly 1,000-6,500 gallons of oil per acre in a single year. But compare that to soybeans. It manages about 48 to 66 gallons per acre. Even palm oil sits far below algae. So theoretically, algae fuel ranks above the two problems that sink most crop-based renewable fuel:
- No food competition: You aren’t turning cropland or dinner-plate calories into jet fuel, which is the criticism that has dogged first-generation biofuel for years.
- No prime land needed: Algae grows in ponds, tanks, or bioreactors, and many strains thrive in wastewater or saltwater, so it does not fight agriculture for freshwater or fertile soil.
There’s a bonus that makes climate people especially excited: algae eat CO2 as it grows. In theory, you could park a cultivation system next to a power plant or factory and feed it the flue gas, turning an emissions source into feedstock.
But here’s the catch. None of this is happening at commercial aviation scale yet. Airlines have burned algae-derived blends in test flights (during 2011 to 2015, more than 2,500 commercial flights used biojet blends from feedstocks including algae), but there’s not a single plant pumping out algae-based SAF by the millions of gallons. The yield is spectacular. But the economics are surely not.
Algae Fuel vs. Traditional Biofuel Feedstocks
The cleanest way to see where algae stands is to line it up against the two feedstock generations already in the tank.
| Feedstock | Example | Oil yield (gal/acre/yr) | Food or land competition | SAF status today |
| First-generation | Soybean, palm oil | ~48 to 635 | High (uses cropland) | Limited by sustainability rules |
| Second-generation | Used cooking oil, animal fats | N/A (waste stream) | None | Dominant (~80% via HEFA) |
| Algae | Microalgae strains | ~1,000 to 6,500 | None | Pre-commercial, high cost |
The pattern is clear. Waste oils win today because they’re cheap and already collected. Algae wins on paper because of its yield and land use. The whole bet is whether algae can close the cost gap before the waste-oil supply runs dry, which it will, because there’s only so much used cooking oil in the world.
The Green Technology Turning Algae Into Aviation Fuel
Sourcing algae from a pond to convert it into jet-grade fuel is a multi-step process, and each step is a place where cost creeps in. Here’s the pipeline:
- Strain selection: Pick any microalgae that grow fast and pack in lipids. Some strains hit 50 to 70% oil by dry weight.
- Cultivation: Grow it in open ponds or closed photobioreactors. However, open systems cost roughly a tenth of closed ones per unit area.
- Harvesting and dewatering: Separate the algae from the water. This is energy-hungry and one of the sneakiest cost drivers, because you are moving a lot of water to recover a little biomass.
- Lipid extraction: Pull the oil out of the cells.
- Refining to jet spec: Upgrade that oil into a fuel that meets aviation standards, usually via the same hydroprocessing that HEFA uses.

Companies are trying to fix the problem from different angles. HutanBio, for example, focuses on a marine microalgae strain it says can grow on non-arable land with seawater, sidestepping the freshwater and land costs that sank earlier attempts. European research consortia are chasing the same cultivation-to-fuel chain with public funding, and several are testing co-location with CO2 sources to cut both feedstock and emissions at once. But the hardest part is doing all of them together, at scale, for a price airlines will actually pay.
Why the Third Wave of Algae Fuel Might Finally Succeed
I’m a bit skeptical of this algae hype because we’ve been here before, twice.
The first wave was the U.S. Department of Energy’s Aquatic Species Program in the 1980s and 1990s, which spent nearly two decades on algae and ultimately concluded that it was too expensive at the oil prices of the era. The second wave hit in the 2000s and early 2010s, when venture money and even oil majors like ExxonMobil poured into algae startups chasing a cheap crude replacement. Then oil prices fell, production costs stayed brutal (one estimate put algal oil at around $10.50 per gallon from a photobioreactor), the promised timelines slipped, and the money left.
So why would a third wave be different? The argument presented by HutanBio is that the surrounding conditions have changed:
- The target moved: The first two waves aimed at cheap ground fuel, competing directly with gasoline and diesel. This one aims at aviation, where there is no easy electrification alternative, and buyers will pay a premium they would never pay at the pump.
- Carbon now has a price: Mandates and carbon costs change the math that killed earlier ventures. A fuel that was uneconomic against $2 diesel can pencil out against mandated SAF demand.
- The tech matured: Better strains, cheaper renewable electricity for processing, and improved bioreactor designs all chip away at the cost curve that once used to be a cliff.
I wouldn’t bet the house on it. But same idea, completely different market is a more honest case than this time the science finally works, and it’s why algae keeps showing up in serious decarbonization conversations instead of being written off for good.
SAF and Aviation’s Decarbonization Targets
So, here’s the climate case.
Aviation is about 2.5% of global CO2 emissions, and closer to 4% of actual warming once you count other factors, like contrails and some other non-CO2 effects. That sounds small, but flying’s one of the toughest sectors to decarbonize, because batteries are too heavy for long-haul and roughly 80% of aviation emissions come from flights over 1,500 km where there’s no realistic alternative to liquid fuel.

And the worst part? The sector’s still growing. On today’s technology, air traffic could generate around 2 billion tons of CO2 a year by 2050, more than double 2019 levels.
That’s why SAF carries so much weight in the industry’s net-zero-by-2050 plan. On lifecycle emissions:
- SAF typically cuts CO2 by up to around 80% versus fossil aviation fuel, and up to 94% with the best feedstock and process, per DOE figures.
- Those cuts are not automatic. Real reductions depend heavily on the feedstock and how much energy the production uses. A dirty power grid or a land-use-heavy feedstock eats into the benefit fast.
But here are some interesting numbers. IATA estimates SAF could deliver around 65% of the emissions cuts needed to get aviation to net zero. Not all of it, since fleet efficiency and offsets carry the rest, but more than any other single lever. The problem is that the lever is barely being pulled yet, and the reason is money.
Barriers to SAF Adoption & Aviation Sustainability
Cost is the wall. SAF is several times more expensive than conventional jet fuel. EASA has pegged it at roughly 3-10X pricier depending on the current pathway. And when SAF costs a multiple of the fossil alternative and fuel is an airline’s single largest variable cost, adoption will fall by the wayside.
Cost isn’t the only barrier to aviation sustainability, though. The others compound it:
- Feedstock supply: HEFA depends on used cooking oil and animal fats, and there is only so much of that on Earth. This is exactly the ceiling algae and e-fuels are meant to break.
- Capital and scale: IATA estimates the world needs thousands of new renewable fuel plants to hit net zero, at a level of capital investment that doesn’t exist yet.
- Slow ramp: SAF production in 2024 came in below IATA’s own forecasts as U.S. plants pushed back their timelines.
- Blend limits: With SAF capped near 50% in most engines, even a plane “flying on SAF” is still burning a lot of kerosene until standards and supply catch up.
But SAF still emits CO2 when you burn it. The savings are upstream, in using recycled or renewable carbon instead of fossil carbon. It’s a genuine improvement, but not a zero. And for a short domestic hop, taking a train will almost always beat any renewable fuel on emissions. Anyone selling you guilt-free flying is overselling.
Policy & Market Outlook for Renewable Aviation Fuel
If cost is the wall, policy is the ladder, and this is where the momentum actually is.
Europe is leading with hard mandates. The EU’s ReFuelEU Aviation regulation requires suppliers to blend a rising share of SAF into aviation fuel:
- 2% in 2025
- 6% by 2030 (with a 1.2% sub-target for synthetic e-fuels)
- 20% by 2035
- 70% by 2050
The UK runs its own SAF mandate starting at 2% in 2025 and climbing to 10% by 2030. The U.S. takes the carrot approach instead of the stick, with SAF tax credits and a “Grand Challenge” targeting 3 billion gallons of production by 2030.
The market is moving with the policy:
- Airlines are locking in supply. Delta has signed offtake deals totaling hundreds of millions of gallons, and United committed to 10 million gallons of SAF for 2025.
- Producers like Neste are expanding refineries in Singapore and Rotterdam to feed the demand, and investment funds like the Airbus-anchored SAF Financing Alliance are steering capital toward new production.
- Europe is funding algae specifically. Public research programs are betting on green algae as a next-wave feedstock precisely because waste oils cannot scale to those 2050 targets alone.
In my opinion, mandates guarantee demand, but they haven’t yet cracked the supply problem. Producers are being told to make more SAF than the current feedstock base can support, which is exactly the pressure that could finally pull algae fuel and e-fuels off the lab bench and into a refinery.
Final Thought
So, will your next flight run on algae?
Almost certainly not, and probably not the flight after that either. Algae fuel is still years away from getting into the fuel tanks, that too on a commercial scale. And the algae revolution narrative tends to get ahead of the plant that would actually make it.
But that’s the wrong thing to fixate on. Sustainable Aviation Fuel is already in the system, already cutting emissions, and already the aviation industry’s most credible path to decarbonization. Algae is just one promising lane in that effort, not the whole highway. The interesting question isn’t whether we’re flying on pond scum next summer. It’s whether the mandates, the money, and the green technology line up fast enough to make it boring by 2040. And if they do, that’s the win.
FAQs
Test flights only; don’t use for regular service. Despite their flight, no plant is able to produce algal fuel at commercial aviation scale. Nearly all SAF produced today is from waste oils and fats.
The major use is mostly cooking oil, animal fats, and plant oils through the HEFA pathway, which is about 80%. Other routes involve using green hydrogen with captured CO2 or farm waste or alcohol.
Multiple times higher; some estimates are 3-10 times as much as regular aviation fuel based on the route. The primary problem with adoption is cost.
No. SAF still emits CO2 when burned, but its lifecycle footprint is up to around 80% lower because it uses recycled or renewable carbon instead of fossil carbon.
IATA estimates Sustainable Aviation Fuel could deliver roughly 65% of the emissions reductions needed for aviation to reach net zero by 2050.
Large companies such as United and Delta have purchased AF, and entered into large offtake agreements with many others. Blending of SAF has been mandated at selected airports across the EU and UK.
